AboutGet the overview
For student-athletes and the people who advise them

Your NIL years can
pay you for life.

Set aside a small fraction of NIL income now. It’s built to pay you potential tax-free income later, long after the games are over.

Go pro or not, every athletic career ends someday. And most careers after sports don’t come with a pension.

How it works

Fund it once. Let it work.

The NIL Pension is built on a life insurance policy designed to build cash value and pay income later. Three stages, one simple idea.

In college

Fund it

Set aside a small portion of NIL or revenue-share income. That’s the only money you put in.

Through your career

Let it grow

Nothing more out of pocket. Your policy does the work while your career and life move forward.

When you need it

Take income

Optional income, potentially tax-free. You choose when to start, and it can last through retirement.

A hypothetical example

A small slice. A big difference.

Set aside over two college years$200,000$100,000 a year at ages 19 and 20, a portion of NIL income
Potential tax-free income$123,507 a yearIn this example, starting at age 45
Potential cumulative income$6,916,365Ages 45 to 100, 56 years of income

In the same example, a taxable investment account nets about $3.28 million over the same years.

Hypothetical illustration only. Not a guarantee. In this example income begins at 45, but it can begin sooner or later. See important information below.

Choose your path

Who is this for?

Build something that outlasts your career

  • Use a fraction of your NIL income, not all of it.
  • It’s one more asset, built while you’re still in college. It doesn’t depend on how long your playing career lasts.
  • Income later in life is optional and potentially tax-free.
  • Talk it over with someone you trust and a tax professional first.

Get the athlete overview

For parents, agents and financial advisors

  • A clear way to help an athlete turn a few strong earning years into long-term retirement income.
  • Uses only a small portion of NIL or revenue-share income.
  • Fits athletes who may not have a pension elsewhere in their professional life.
  • Easy to explain: fund early, nothing more out of pocket, optional income later.

Get the advisor overview

About us

Why I do this

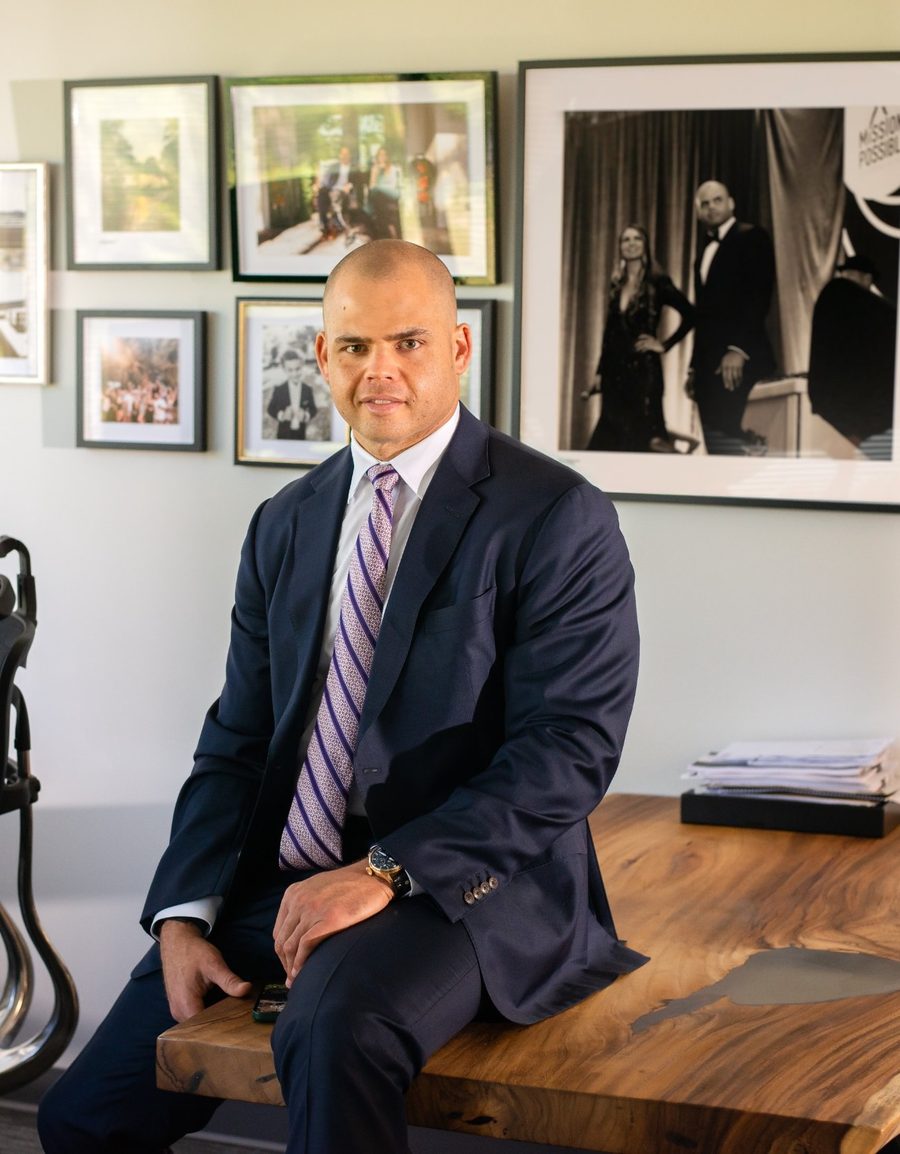
Jeff Faine, founder of Integrated Planning Partners

Jeff Faine, CLU

Founder, Integrated Planning Partners

I’m a Notre Dame alumnus and a former NFL offensive lineman, with stops with the Cleveland Browns, New Orleans Saints, Tampa Bay Buccaneers and Cincinnati Bengals.

On the offensive line, my job was to protect others and create opportunities for them. That’s the reason I entered financial services in the first place.

It extends to the athletes we work with. The work they do on the court and the field should pay off for them long after their playing days have ended. NIL Pension is one way we make that happen.

I’m also the author of The Architecture of Retirement and co-founder of The Faine House, a nonprofit supporting young adults aging out of foster care. NIL Pension is a solution of Integrated Planning Partners, the firm I founded.